Are you thinking of buying to let and building a property portfolio? Then you are in the right place..
The UK property market is changing. The average UK house price was £273,000 in July 2026, which is 1% higher than a year earlier, and prices fell over the year in London and the South West (HM Land Registry; House of Commons Library).
Meanwhile, landlords are selling up. Savills estimates that 254,000 previously rented homes were listed for sale across Great Britain in the 12 months to March 2026. That would be around 700 a day, and 9% more than the year before. For a lot of people, the trigger was the Renters’ Rights Act. From 1st May 2026, it abolished Section 21 “no-fault” evictions in England and changed fixed-term tenancies into rolling ones. (GOV.UK).
The tax rules have also been changing. Section 24 replaced the mortgage interest relief with a 20% tax credit. So from April 2027, property income tax rates rise by two percentage points, meaning personal rental profits can be taxed up to 47%. (GOV.UK)
For landlords who are staying in the market, their question now is how property should be held. It is one of the questions we hear most often at Fynax. Landlords contact us at every stage, from first-time investors buying a single buy-to-let to established owners with a growing portfolio. They all have the same main concern: should I own my property personally or through a limited company? And the answer is that there is no single right answer, as it depends on your income and your plans. So, let’s weigh up the personal versus limited company ownership across our recommended 7 key factors.
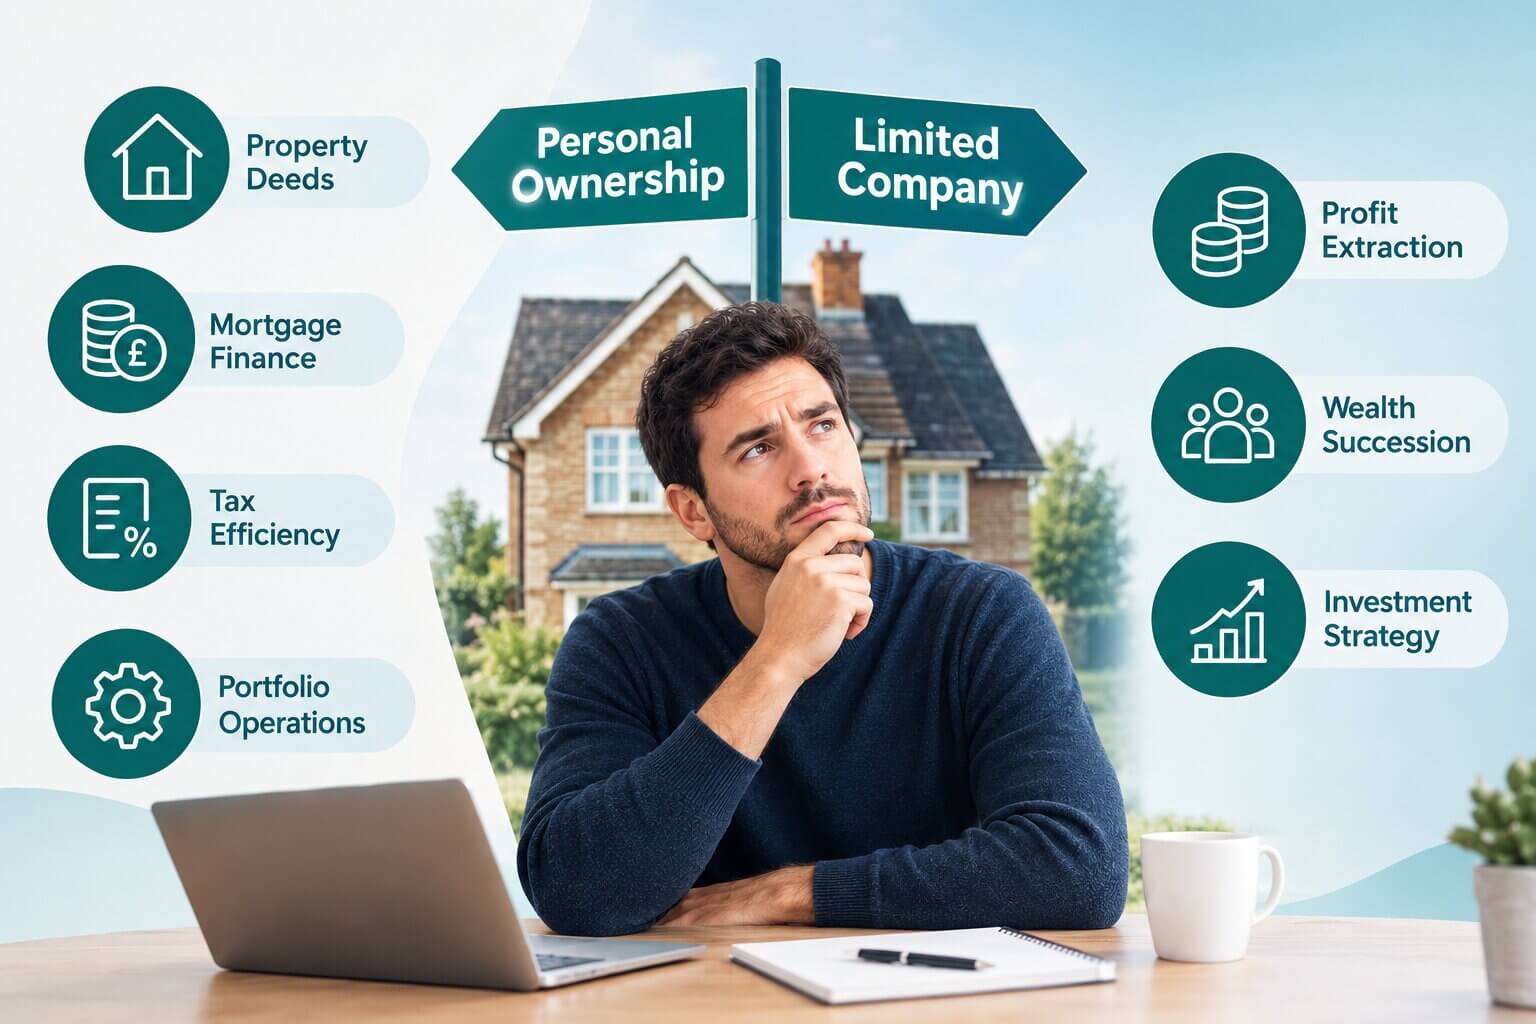
Buy To Let Property Personal Vs Ltd by Fynax
1. Property Deeds
When you buy a property in your own name, the deeds and the mortgage are registered to you. It is the simplest and more private route since nothing about your rental income will appear on a public register. However, the disadvantage is that you’re personally liable for any debts or legal claims that are connected to the property.
With a limited company, the company owns the property, and you own shares in the company. As the company is a separate legal entity, your personal assets are protected if something were to go wrong. It is also more flexible, as you can bring in a spouse, children or investors as shareholders. The disadvantage is that, as directors and shareholders, your annual accounts will be visible on the public record at Companies House
2. Mortgage Finance
Personal buy-to-let borrowers generally enjoy a wider choice of products, slightly lower interest rates, and a simpler application process. However, for higher-rate taxpayers, personal ownership has become highly restrictive.
While limited company mortgages carry slightly higher interest rates (typically 0.2% to 0.5% more expensive) and higher setup fees, they offer massive structural benefits. Beyond allowing landlords to deduct 100% of mortgage interest as a business expense, companies benefit from much more generous lender affordability “stress tests”, often allowing landlords to borrow more capital than they could personally. Landlords should note that lenders will almost always require directors to sign a personal guarantee, and a standard 25% deposit remains the industry baseline for both routes.
3. Tax Efficiency
If you own personally, your rental profit is added to your other income and is taxed at your marginal rate. Mortgage interest only earns a 20% tax credit. However, from April 2027, property income will move into its own higher rates of 22%, 42% and 47% (HMRC: Tax Rates Changes for property). When you decide to sell, you pay Capital Gains Tax at 18% or 24% after the £3,000 annual allowance (HMRC: Capital Gains Tax). For a basic-rate taxpayer with a single property who does not intend to cross into higher income brackets, personal ownership remains a highly viable and cheaper option
Conversely, a limited company pays Corporation Tax on its rental profits after deducting all allowable expenses, including 100% of the mortgage interest. Net profits up to £50,000 are taxed at 19%, which slides up to 25% for profits above £250,000, mitigated by marginal relief in between (GOV.UK: Corporation Tax Rates). For a corporate entity, capital gains upon a sale are taxed at these exact same Corporation Tax rates with no annual tax-free allowance. Landlords must note, however, that extracting profits from a company structure will subsequently trigger personal dividend or salary tax, meaning corporate wrappers are primarily ideal for portfolio growth and reinvestment rather than personal spending. If this feels overwhelming, you are not alone; our corporate tax accountants have spent the last 20 years helping thousands of landlords navigate their business tax planning confidently.
4. Portfolio Operations
In the old days, holding property personally meant a minimal administrative burden; landlords simply reported their rental income via a standard annual Self Assessment tax return. However, the introduction of Making Tax Digital (MTD) for Income Tax has fundamentally altered this landscape. Landlords with qualifying property income above the statutory thresholds are now required to maintain digital records and submit mandatory quarterly updates using HMRC-compatible software, followed by a final end-of-period submission. This phased rollout narrows the operational gap, bringing the administration of personal ownership significantly closer to that of running a limited company. For more information, check our Making Tax Digital for landlords and sole traders blog.
Owning through a company brings some extra filing requirements. Each year, it must file statutory accounts alongside a confirmation statement with Companies House, and a Corporation Tax return with HMRC. In addition to this, you’ll still need your own Self Assessment return for any dividends you choose to take. Then there are the running costs of accountancy fees and Companies House fees.
5. Profit Extraction
With personal ownership, once tax is paid, the rent is yours to spend however you’d like. There is no further tax.
With a company, the profit will belong to the company, so taking the money out will need some business tax planning. You can pay yourself dividends or draw a small salary; you can also have the company repay any money which you lent it, such as the original deposit, which will come back to you tax free. Dividends, however, do result in double taxation, as the company pays Corporation Tax first, and then you pay dividend tax on what you take out. The advantage comes when the rental profits stay in the company to invest and purchase your buy to let properties.
6. Wealth Succession
Properties that you own personally will form part of your estate. Anything that is above the £325,000 nil-rate band can face Inheritance Tax at 40%. Giving a property away in your lifetime can trigger Capital Gains Tax too.
A company gives you more room to plan. Instead of handing over whole houses, you can pass shares to your children or grandchildren while the company keeps running. However, a company does not make your portfolio free of Inheritance Tax. Letting companies don’t usually qualify for Business relief, so the benefit is mainly in flexibility, not exemption.
7. Investment Strategy
Personal ownership tends to suit those looking for a short term option. Someone with a single property and a single rate taxpayer. It also makes sense if you plan to sell the property within a few years, since you’d be able to keep the £3,000 CGT allowance.
A limited company is better for someone looking for a long-term option. If you’re a higher rate taxpayer, relying on mortgages and planning to build a larger portfolio, a limited company is usually the best option for you. However, if you already own a property personally, proceed with caution. Moving the existing property into a company will be treated as a sale and can trigger both Capital Gains Tax and Stamp Duty Land Tax. Unsure how to approach your portfolio? Book your free consultation today with the fynax team
Our Client Story
The client challenge
Our client is an experienced entrepreneur who has run several successful businesses over the past couple of years. In 2020, they decided to diversify and start investing in residential rental property. As their business income already put them in the higher-rate tax band, they knew this would mean buying in their own name would result in paying 40% tax on any rental profits. It also meant they would lose full relief on mortgage interest.
They had plenty of business experience but had never structured their property portfolio before. They weren’t sure whether a limited company was worth the extra admin.
Our Approach
We started with a review of their personal tax position and their long-term plans. They wanted to buy several properties over the following years, reinvest their profits and eventually pass on their portfolio to their children. Then, we modelled the expected tax on a typical buy-to-let under personal ownership and under a limited company, including the higher mortgage rates.
The comparison between the two showed that a company made sense for their goals. We set up a special purpose vehicle (SPV), registered it under the specific SIC code, and registered for Corporation Tax. We also structured the deposit funding as a director’s loan, so the money could be repaid to them tax-free later.
The solution and results
Now, the company owns rental properties. Rental profits are taxed at the 19% small profits rate and kept in the company to fund every new deposit. Buying in their own name, those profits would have been taxed at 40% with a restricted mortgage interest relief.
Fynax now handles the company’s bookkeeping, statutory accounts, confirmation statement and Corporation Tax, as well as the client’s personal Self Assessment. The company has met every filing deadline without a penalty, and each year we review the portfolio with the client to plan the next purchase.
In Summary
Personal ownership is simpler, cheaper to finance, and more private. It suits a basic-rate taxpayer with one property who needs the income now. Conversely, a limited company is suitable for landlords with future investment plans to grow a portfolio. It costs more to run and borrow, and taking profits out triggers a second layer of tax. In return, however, it gives you full mortgage interest relief, lower tax on profits you reinvest, limited liability, and more flexibility when passing wealth on.
At Fynax, we encourage landlords who want to build a portfolio to switch to a limited company for their future purchases. If you already own a property personally, get your free consultation today. We’ll help you work out whether moving it is worth the tax cost. Talk to us before you buy, and we’ll run the numbers for you.